
 Contacto
 Como comprar

Entrega
Guia de compras
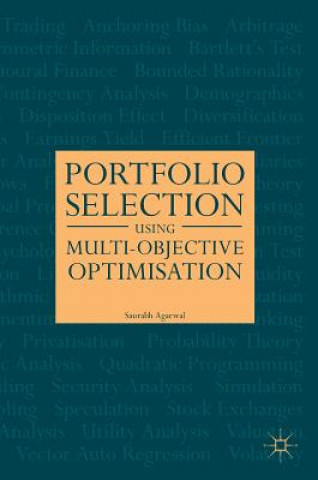
Portfolio Selection Using Multi-Objective Optimisation
 Inglês
 325 b
Até 30 dias para devoluções
Os clientes também compraram




 /
 Capa mole
 15.48
€

 /
Capa mole
21.82
€


 /
Capa mole
15.78
€
 /
Livro de capa dura
124.70
€




 /
Capa mole
24.13
€

This book explores the risk-return paradox in portfolio selection by incorporating multi-objective criteria. Empirical research is presented on the development of alternate portfolio models and their relative performance in the risk/return framework to provide solutions to multi-objective optimization. Next to outlining techniques for undertaking individual investor's profiling and portfolio programming, it also offers a new and practical approach for multi-objective portfolio optimization. This book will be of interest to Foreign Institutional Investors (FIIs), Mutual Funds, investors, and researchers and students in the field.


Sobre o livro
Inglês

Ofereça este livro hoje
É fácil
1 Adicione ao carrinho e escolha Entregar como presente ao finalizar a compra 2 Receberá um vale 3 O livro chegará ao endereço do destinatárioTambém pode estar interessado em
 /
 Adobe ePub DRM
106.34
€
 /
Capa mole
72.71
€
 /
Capa mole
43.66
€
 /
Capa mole
187.06
€


Olá! Sou o Libroamiko, o seu conselheiro de livros.
Como posso ajudar?