
 Contacto
 Como comprar

Entrega
Guia de compras
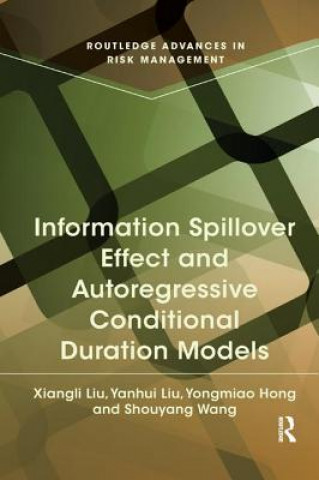
Information Spillover Effect and Autoregressive Conditional Duration Models
 Inglês
 174 b
Até 30 dias para devoluções
Os clientes também compraram



 /
 Capa mole
 17.99
€











 /
Capa mole
26.34
€

 /
Capa mole
16.28
€

This book studies the information spillover among financial markets and explores the intraday effect and ACD models with high frequency data. This book also contributes theoretically by providing a new statistical methodology with comparative advantages for analyzing co-movements between two time series. It explores this new method by testing the information spillover between the Chinese stock market and the international market, futures market and spot market. Using the high frequency data, this book investigates the intraday effect and examines which type of ACD model is particularly suited in capturing financial duration dynamics.
The book will be of invaluable use to scholars and graduate students interested in co-movements among different financial markets and financial market microstructure and to investors and regulation departments looking to improve their risk management.


Sobre o livro
Inglês

Ofereça este livro hoje
É fácil
1 Adicione ao carrinho e escolha Entregar como presente ao finalizar a compra 2 Receberá um vale 3 O livro chegará ao endereço do destinatárioTambém pode estar interessado em

 /
Livro de capa dura
33.28
€



 /
Capa mole
90.51
€






 /
Capa mole
12.86
€
 /
Capa mole
28.65
€
 /
Capa mole
52.39
€

Olá! Sou o Libroamiko, o seu conselheiro de livros.
Como posso ajudar?