
 Contacto
 Como comprar

Entrega
Guia de compras
 Inglês
 393 b
Até 30 dias para devoluções
Os clientes também compraram




 /
 Capa mole
 21.85
€
 /
Capa mole
45.11
€


 /
Capa mole
55.69
€


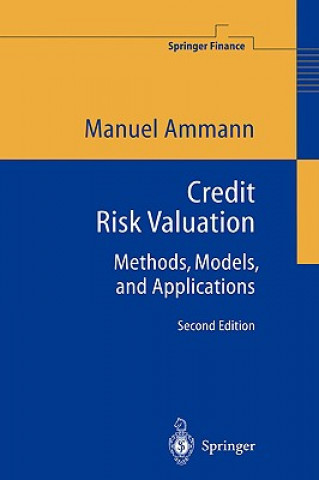
This book offers an advanced introduction to the models of cre- dit risk valuation. It concentrates on firm-value and reducedform approaches and their applications in practice. Additionally, the book includes new models for valuing derivative securities with credit risk, focussing on options and forward contracts subject to counterparty default risk, but also treating options on creditrisky bonds and credit derivatives. The text provides detailed descriptions of the state-of-the-art martingale methods and advanced numerical implementations based on multi-variate trees used to price derivative credit risk. Numerical examples illustrate the effects of credit risk on the prices of financial derivatives.


Sobre o livro
Inglês

Ofereça este livro hoje
É fácil
1 Adicione ao carrinho e escolha Entregar como presente ao finalizar a compra 2 Receberá um vale 3 O livro chegará ao endereço do destinatárioTambém pode estar interessado em



 /
Capa mole
18.02
€


 /
Capa mole
51.26
€
 /
Capa mole
76.13
€




 /
Capa mole
56.49
€

Olá! Sou o Libroamiko, o seu conselheiro de livros.
Como posso ajudar?